Why Actual Cash Value (ACV) is Failing Drivers
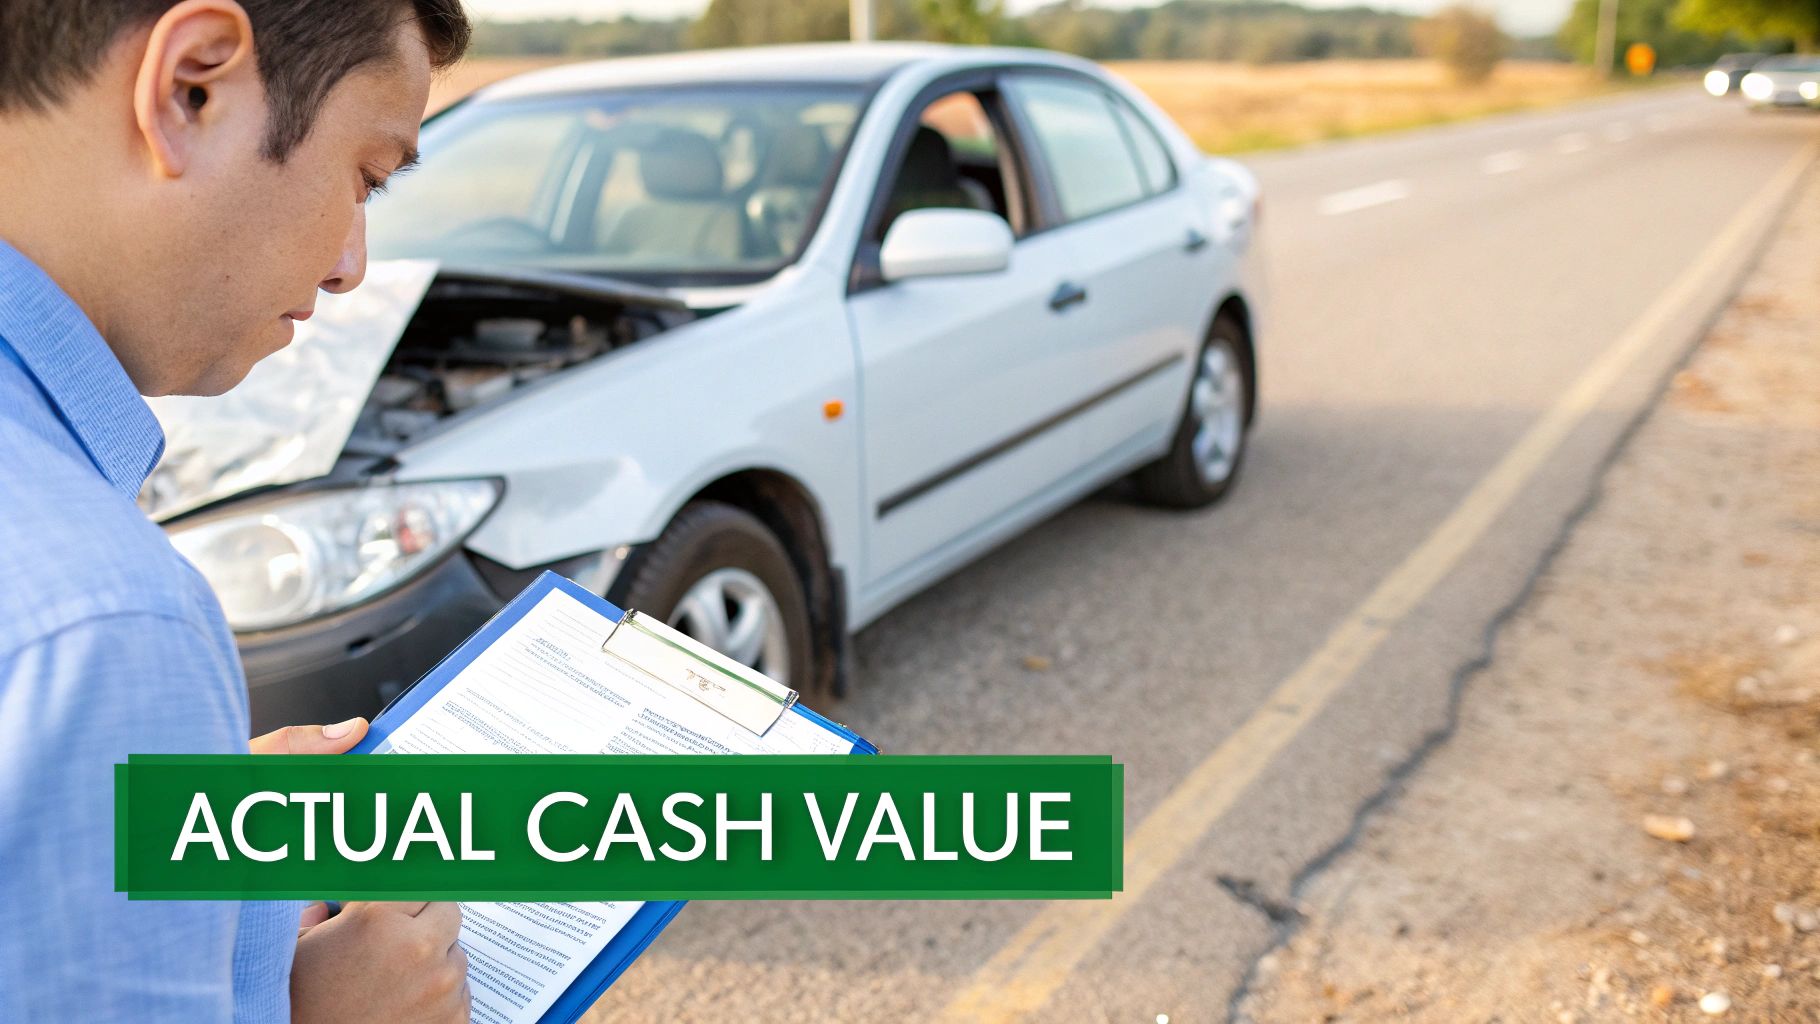
For decades, Actual Cash Value (ACV) was the industry standard. It pays you what the car is worth today (Replacement Cost minus Depreciation). But in 2026, with the high cost of tech-heavy vehicles and the volatility of the used car market, ACV is leaving many drivers with a massive “financial gap.”

The Shift to Agreed Value In 2026, “Agreed Value” policies—once reserved only for classic Ferraris—are becoming popular for high-end EVs and customized trucks.
- Fixed Payouts: You and the insurer agree on a set value (e.g., $65,000) when the policy is written. If the car is totaled, that is exactly what you get—no depreciation, no market-haggling.
- Protecting the “Tech Investment”: If you’ve spent $10,000 on software unlocks or aftermarket long-range batteries, an ACV policy will likely ignore them. An Agreed Value policy locks them in.
The Bottom Line: While the premium for an Agreed Value policy in 2026 is roughly 15% higher, it is the only way to ensure that a “Total Loss” doesn’t become a “Total Financial Disaster.”